Posts

Showing posts with the label M1

War Among the Titans
Image
This article contains PART of my 1st Scorecard Newsletter written on 22 Aug 2018 for my Moat Scorecard subscribers.  This is the 1st write up of the Scorecard Newsletter just for you, as a subscriber.  This write up will comes with full disclosure on the companies that I will be discussing, even if they are in my portfolio. Do note that this write up will be reproduced on TUB Investing Blog 1 month later without full disclosure. Before I start, I like to discuss about the consequences that occurred during the Turkey-US crisis.  Basically, market went down quite drastically and it caught quite us by surprise. This signifies the volatility of the current market – a simple discussion between countries can result in multiple ripples globally.  This is most probably the Nth time I had said it – as a retail investor, we need to invest in a strong fundamental company to be able to avoid these ripple effect. Companies with strong moat will have strong fundamental...
The Dilemma

Image
Since I have been such a supporter of  M1 Ltd in my previous posts, I suppose I should announce that I have sold all my holdings in the company. Nevertheless, due to this action, I had friends questioning if I had become a trader? So HAVE I? Today, I managed to converse with a trader and an investor. They gave me 2 different perspectives that is the exact opposite of each other. Do note that both of them are making money currently. Picture taken from Quora Trader's comment: I have a small capital. Thus, trading is the way for me. Contra trade do not need capital. I only trade blue chips or REITs, and I place a stop loss and target price for every trade, so I wouldn't hold any trade. I do invest, as well, for mid term (2 to 3 months) and long term (6 to 8 months) . Usually I try not to hold a share for too long, unless I feel it has the potential to be a multibagger. The market is very volatile right now, most people will take profits and protect profits. There...

Review Of M1 Limited Q1 Results

Image
Before I go into the main topic, I will like to clarify some queries on Fundamental Scorecard website . People had asked if Fundamental Scorecard requires users to key in any data?  I like to use this opportunity to clarify that THE ANSWER IS NO! Fundamental Scorecard website's data is already pre-loaded. Eventually each counter will have its own report with the scoring from the pre-loaded data. You do not need to key in any information! Ok...back to the main topic. M1 Limited (aka M1) just released its Q1 report this evening. Basically, revenue and net profit remains flat. But I like to bring reader's attention to the following 2 slides: Revenue Cost of Goods Sold If we compare the revenue between Q1FY2017 and Q1FY2018, Mobile Services had increased from $137M to $141M. Fixed Services had also increased from $28M to $32M. Then if we compare the Cost of Goods Sold (COGS) between Q1FY2017 and Q1FY2018, Fixed Services' COGS remains flat desp...

Singtel, M1 and Starhub – Which Should I Invest In?

Image
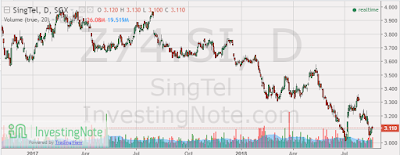
Once the darlings of many of the Singapore retail investors for their defensive nature and high dividend yield, telco counters’ share price had come down drastically after the announcement of the 4th Telco. Market share of these 3 incumbent telco counters are further reduced by the introduction of Mobile Virtual Network Operator ( MVNO ) , Circle Life, Zero Mobile, Zero1 and maybe  MyRepublic. However, being a believer of value investing and contrarian investing and maybe moat investing, I still believe that every counter does have a fair price. When the negativity of a counter is at its highest, when no one talks about it anymore, when the share price has been stagnant for a long time, the bottom could possibility been reached. I believe that is when one should pounced on the counter. However, these 3 counters are currently trading at their multi-year low share price. Which one should I choose? Rather than assets, my opinion is these Telco should be measured by their ab...

My View On M1 Latest Earning Report

Image
Since I have written about M1 Ltd (aka M1) in my last post, I felt I should be responsible to write something about its latest full year 2017 earnings report. Firstly, I am delighted. This was because dividend (for the 2nd half of the year) increased, even when the 4th quarter net profit was slightly lower than the year before. In addition, everyone was expecting a lousy quarter because IT IS M1 -  the telecom that is bound to fail! If the results were lousy, everyone will just be like "I told you so..." ; but now everyone is more like "hmmm... is this good or not good?" , just like all the analyst in this article. But What Is My Opinion of M1's Future? Despite being vested in M1, I am VERY SURE its revenue will be impacted by the entry of TPG and MyRepublic this year. Thus, M1's current diversification into IoT is to minimize the impact of the loss of market share within its Telecom business. This should not be seem as a new revenue c...

I Repurchased M1 Again!

Image
2 posts ago, I asked readers to choose a counter, that I bought recently, to review. Many commented on CWX Global Limited, which I believe I had already explained quite significantly in that particular post. Therefore, I was reluctant to write about it. Luckily, someone else commented on M1 Limited (aka M1) and so here we go... If you remembered, I wrote about selling all of M1 and keeping ComfortDelGro Corporation Limited (aka Comfort) in September 2017. As of today, I have sold all of Comfort and have repurchased M1. Within a 2 year period, I made some money on M1 but will have also made losses on Comfort. You must have thought why am I doing this – Selling Comfort when Uberflash has been launched, and when they have already established contact with Uber. The main reason was that I do not like Comfort's deal with Uber - such as where will the money come from? Will there be a lowering of dividend? In my opinion, I don't think the bottom has reached yet and it will st...

What Had I Been Up To?

Image
Firstly, before I start, it will be good to inform everyone again on our Face-to Face Ask-Us-Anything session on 16 Jan 2018. Details of the event are listed in this post . If you are interested to come, just come along that evening. So What Had I Done Since The Last Post? Although I have said in my 1st post of 2018 that I felt the market is boring, but at this point, I had already made A LOT OF PURCHASES . As stated in the same post, I ventured actively into the US and HK Market. In addition, I had also tweaked some of my thoughts about the SG market and made some purchases. This came about after I decided I was STILL holding too much cash after venturing overseas  (I had about 40% to 50% of my portfolio) . In this case, I decided to make some short term investment into companies that are getting into certain "situations". This was not what I planned at the start of the year and I was taking more risk investing in these companies. However, I see the taking of ...

Why I Choose ComfortDelGro Over M1

Image
This will be a follow up of my previous post as I talk about the sick Blue Chips in my portfolio. After my last review of my portfolio, I kept thinking of what to do with my sick Blue Chips. I believe that I should reduce the number sick Blue Chips in my portfolio. Eventually, it was a decision to keep either ComfortDelGro or M1 . By the time you read this, and as the title suggest, I will have already sold off all my M1 shares. So why did I choose ComfortDelGro over M1? 1. I have Singtel and M1.  Since I already have 2 telecommunication companies in my portfolio, and this industry will be impacted in the future, I decided to just keep 1 of them in my portfolio. 2. ComfortDelGro is a much bigger company! Other than market cap, ComfortDelGro is a much bigger firm than M1. ComfortDelGro owns part of VICOM and SBS Transit. But M1 is just M1. 3. ComfortDelGro has been increasing their dividend, while M1 has been reducing their dividend. 4. The ...

Battling On 4 Fronts

Image
Other than busy with changes in T.U.B Circle and Super Scorecard , I have also gotten my keys to my HDB BTO flat. Thus, these few weeks I will be extremely busy and I apologize for a lack of updates in this blog. But don't worry, as the post on the upgraded scorecard and the post on the new "technology" counter that I invested in will be out soon! Nowadays, market has been stagnant and at times, seems to be on the downtrend. Many of my watchlist counters' prices are at very tempting level for me to enter. But my portfolio is currently already engaged in 4 different "battles"! Battle 1 - Netlink Trust IPO Application This is the first time I tried applying for placement shares. Thus, I have to allocate some cash for this battle. If I am not allocated any placement shares, then I will apply for the public offer. If this was a week earlier, you will hear me saying that I will not be applying for this IPO. However, this IPO seems like it will be ...

M1 Ltd - A Different Perspective

Image
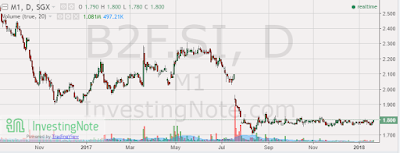
M1 Ltd  has been falling for a prolonged period, from the heights of $3.930 on April 2015, till $2.020 on 31 Oct 2016, before recovering slightly recently. Over the period of freefall, there was also a slight recovery during this period of fall. Nevertheless, as per the chart below, the share price is currently at the lowest point over the last 5 years. Why? Many factors has caused this downfall, such as the pending establishment of the 4th Telco, the Jan-Feb 2016 correction, the insider selling by the CEO and also the recently released 3rd Quarter financials which were deem to be "very poor". These factors were further enhanced by analyst reports that states M1 Ltd will be the worst hit among the 3 Telcos. Yes, people continues to be "addicted" to analyst reports . So there are some truth... 1. M1 will be the most badly hit by the emergence of 4th Telco - This factor, as reported by many analyst reports, is due to M1's busine...

Target Price During This Crazy Time

When Japan announced that they are adopting negative interest rate , I decided that a new era has arrived. Imagine lending $100k to expand your business, and after 5 years, you only need to return $100k or maybe slight higher. Cost of borrowing will have really gone down for the corporates and even the savers. Individuals, who are savers, will have to find alternatives to get more return. Stock Market around the world has been very volatile - I really don't know what will happen tomorrow. Instead of doing an analysis individually, I rush through the weekend to finish this - Analyse on the stocks I am interested to invest in and find the target price I should enter for that stock. Do note that minimum input was done and business analysis was put aside. The review was just done on the financials.  And also, a mindset was required for this analysis - "Every stock will have an entry price. It is just a matter of how far it is or how near it is from its current price."...

M1 - The First Trial On A Blue-Chip

Image
I will be using M1 as the first company to test my Triple S Scorecard. Profile In Short If you do not know what M1 does or is, you do not know Singapore enough. In simple terms, M1 is still one of the only 3 telecommunication companies in Singapore. Based On Triple S Scorecard: Why So Good? Defensive Stock - Telecom Companies are deem as defensive stocks, due to their business model. It will always have business and its customer are locked up with them for at least 2 years (due to signing up a 2 year mobile plan with M1). 1 of the only 3 Established Telecommunications Company in Singapore - Despite announcement of a 4th Teleco coming along the way, it has been stated widely that M1 may AT MOST LOSS 20% of the revenue. This is due to the fact that Teleco industry has a high barrier to entry. Having established in Singapore for such a LONG TIME, M1 already an established infrastructure. High Dividend Yield, Dividend Payout Company - M1 is a company that p...

M1 - A more extensive explanation

Image
Many of you might have read what I wrote about Singtel  and some of you asked me about my investment in M1 as well. I bought it at 2.66 in Sep 2012 and have been holding on to it since. Every year I received about 4% to 5% of Dividend and I believe this will continue. M1 has always been my prefer choice of local telco investment, prior to the 4th Telco News, because: 1. Cheapest Defensive Stock among the 3 Telcos and with the one with the lowest debt. 2. No Cable TV or Mio TV - With the streaming services readily available on the net, this seems like a lose-making venture, especially with the fighting of the EPL rights. Charging sky high prices towards the consumers will only backfire eventually. 3. First Teleco to step into the fibre boardband spectrum. 4. Consistent Rising Trends. Singtel and Starhub, at that point, has a more roller-coaster trend. So with the news of the 4th Telco (in additional to the Greece Drama as well as the new up and coming China D...