Posts

Restarting on Substack...

Image
It’s good to be back. I’ve finally carved out the time to return to Substack, and I’m hitting the ground running. My latest thesis is the most critical one yet: 2026 is the Year of Rotation. We are witnessing the end of the AI infrastructure obsession and the birth of a new Consumer era. In my first article back, I break down the specific mechanics of this shift: The 6 Pillars of 2026: Why the World Cup and "One Big Beautiful Bill" are the real catalysts. The Monthly War Map: A month-by-month breakdown of market liquidity. I’m excited to share this new chapter with you. Read the 2026 Roadmap and subscribe below: Thank you once again for reading.
Arigato Everyone! A Decade of Blogging!

Image
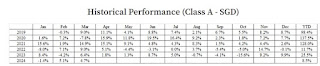
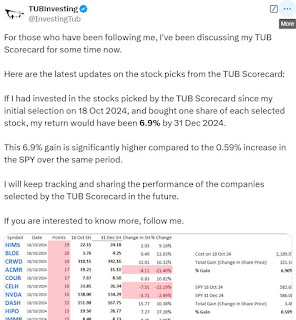
I've been writing since 2015, and this blog has been going strong for almost ten years. Maybe it's time to wrap it up, or perhaps when I find more time. If you've been following me, you've likely noticed I've been pulling back from social media. I've shut down most of my accounts, and there’s been minimal new content on this blog. These days, I'm primarily active on X (formerly Twitter) . Follow me there, and feel free to send me a DM if you want to connect. If you have my phone number, texting is always an option. Just an update: my investment portfolio is still in the red, but it's doubled from its lowest point. Stepping away from social media has probably helped cut through the noise. Before I sign off on this post, I wanted to share that I've gone back to basics and started working on a new scorecard, named the TUB Scorecard, tailored for the US market. It's showing promising results so far without any backtesting; I'm just monitoring it...

Investing in Lincotrade: A Strategic Opportunity Amidst Falling Interest Rates

Image
After the Fed cut rates by 50 basis points last Wednesday , I began exploring industries that might benefit from the potential ongoing interest rate reductions. Specifically, I turned my attention to the construction industry, which investors have largely avoided. With my experience in finance, I understand that this sector in Singapore is currently struggling, and further interest rate cuts could provide much-needed relief. To elaborate, continuously lowering interest rates will boost demand for residential and commercial developments. This increased demand will result in more construction projects and extensions. Consequently, the construction industry will experience growth. Additionally, lower and continuously decreasing interest rates will encourage more economic activity, as money circulates more frequently within the economy. This creates a robust economic environment, leading to higher demand for assets such as property, which in turn revitalizes the construction industry. ...

Geo Energy Resources Laid Foundation for Top and Bottom Line Growth

Image
I have previously written about Geo Energy Resources ("GER") and their most recent half-year 2024 results announcement warrants further examination. At face value, the results appear positive. However, if we exclude "Other Gains", net income would have decreased to US$3.0m. This likely explains the low dividend declared as per the HY2024 report. Geo Energy Resources Income Statement In my view, it is wise to remain cautious given the decline in coal prices from record highs in 2022 to earlier in 2023.  Coal Prices from 2020 till Aug 2024 / Source: tradingeconomics.com That said, acting on impulses to bail out of your position now would be short-sighted. GER future looks promising due to the following reasons: 1. Spike in Energy Demand for South East Asia ("SEA") - Source: 1 , 2 , 3 , 4 , 5 , 6 , 7 The rapid development of AI and data centers in SEA continues to drive up enormous energy needs to power computing infrastructure. As data centers require relia...

Beng Kuang Marine's Strong Half-Year Results and Runway Ahead

Image
I've been extremely busy with work over the last few months. As a result, I didn't realize it had been over 3 months since my last written update on this blog.  Despite that, I decided it was time for a follow up on a company I've been watching closely - Beng Kuang Marine ("BKM").  A lot has happened with their share price since my last write-up . It peaked at over $0.30 after being at $0.168 previously. Now it has pulled back to around $0.210. Beng Kuang Marine Share Price / Source: InvestingNote I distinctly recall the first time I covered BKM back when their share price was just $0.061! They've undoubtedly come a long way since. Most recently on 5 Aug 24, BKM announced their half-year financial results. Beng Kuang Marine Income Statement While the results were impressive, the profit margins alone do not fully capture the significance. Even removing the $5.5 million one-time gain from disposing of the Batam shipyard, BKM remained profitable. This highlights...

Introducing Winking Studios: Navigating the Impact of AI on Art Outsourcing and Game Development

Image
Not Vested Winking Studios (WKS.SI) is a recently listed company in SGX that has made a name for itself as one of the largest Art Outsourcing and Game Development studios in Asia. With a team of highly talented artists and designers, WKS operates across multiple locations, including Singapore, Shanghai, Nanjing, Suzhou, and Taipei. Their impressive clientele boasts 21 of the top 25 game publishers worldwide, highlighting their prominence in the industry. Winking Studios Website Naturally, one might question whether the rise of AI could disrupt WKS business. With the proliferation of art generators and automated tools, it seems plausible that such technologies could threaten the demand for their services. However, WKS has addressed this concern in a detailed article published by Dollars and Senses, providing valuable insights that warrant consideration. While I won't delve into the specifics of their response, I would like to share my thoughts on the matter. The most significant...

The Continuation of Beng Kuang Marine Turnaround Story

Image
Not Vested Since my last write up , Beng Kuang Marine (BKM) has seen a remarkable surge in its share price, soaring from 6.7 cents to 16.5 cents as of today. Additionally, the company has attracted a new institutional investor , which is known for delivering impressive returns. The arrival of this investor suggests that something positive is happening within the company, making it more appealing to potential shareholders. Ginko-AGT Global Growth Fund Returns. Source: AGT Website If you’ve been following my earlier analysis of BKM, you’ve likely benefited from the recent surge in share price. However, it’s crucial to assess whether this upward trend is sustainable. To do so, we need to delve into the company’s fundamentals. After all, I believe the share price surge was driven by BKM’s successful turnaround in FY2023. It’s essential to determine if the underlying fundamentals will continue to improve.  If you're pressed for time , the bottom line is a definite "Yes."  He...

Evaluating Geo Energy Resources' Outlook Post March 2024

Image
Vested Prior to commencing, I must acknowledge that my previous post on Starhill Global REIT received substantial critical responses. Members in my Telegram group (Link in this post ) pointed out loopholes in my article. Specifically, they highlighted that while the REIT boasted high occupancy rates, its revenue from properties outside of Singapore was dwindling. Furthermore, the dividend had experienced a consistent decline over the years, suggesting inadequate management. Hence, if you are contemplating an investment in Starhill REIT, do think twice - although I remain vested for now. On a different note, I previously also wrote about Geo Energy Resource ("GER") (SGX: RE4.SI) , and this article serves as a continuation of my previous piece. Although the time-sensitive information has now been disclosed and March 2024 is coming to an end, I still remain vested in GER.  As we approach the end of March 2024, the question arises: what will happen if I continue to hold onto G...

Riding the REIT Recovery: Why Starhill Global Looks Like an Attractive Purchase

Image
Not Yet Vested (going to buy soon) I believe it is time to re-examine S-REIT companies, as they have been under pressure for an extended period due to the high interest rate environment. I have outlined some criteria for what I am focusing on, such as excluding industrial and office REITs, concentrating on local REITs, and selecting one offering over 6% yield. However, I kept returning to the same S-REIT in which I had invested and written previously. The REIT is Starhill Global REIT (Starhill) . Starhill Global REIT I perceive a generally negative view of this REIT exists, though I feel differently. In my opinion, there are some compelling reasons why it presents such an enticing buying opportunity currently. 1. Interest Rates Expected To Decrease In The Near And Longer Term. I believe the elevated interest rate environment will soon end, and rates will start to drop in the second half of the year overall. This will allow floating debt interest payments to reduce as fixed debt compri...

Geo Energy Resources: A Time Sensitive Trading Opportunity

Image
Vested It has been some time since I last wrote an article on any platform or on this blog. However, I am still been actively managing my portfolio. I just needed some time to recharge, as there were moments when I felt burned out recently. Nevertheless, I have returned and today I will be sharing information about an intriguing trading opportunity. I am currently vested in this company but it represents less than 2% of my portfolio. This is because I have not had any additional funds in my portfolio as my primary goal has been to restore it back to its original value of 100%. Furthermore, this is a trading opportunity and I will most likely sell it prior to April 2024. The Company The company that I would like to discuss is called Geo Energy Resources Ltd ("GER") (SGX: RE4.SI).  The decision to enter into this trade was based on two press releases issued on February 7th and March 1st, 2024 . Image taken from Singapore Business Review To provide a brief overview, there are ...

Revisiting Beng Kuang Marine: Profitability, Disposals, and Potential Opportunities

Image
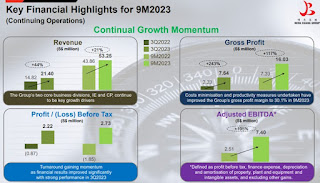
Not Vested. Considering. In my previous blog posts, I mentioned Beng Kuang Marine (BKM) a few times. I initially held a position in the company but divested when its share price increased significantly, as it was only a small portion of my portfolio. Based on my recent review of my portfolio strategy, I am not planning to reinvest in BKM unless it is solely for a separate trade outside of my portfolio. The current circumstances seem to indicate a potential opportunity has arrived. To summarize the situation: BKM has achieved profitability based on its Q3 FY23 results. This suggests that it is highly unlikely for FY23 to be a year of losses for the company.  Source: BKM 3Q & 9m2023 Corporate Highlights Furthermore, BKM has successfully completed the disposal of its tugboats and has received the remaining S$460k in cash. This means that the company's financial results will no longer be negatively impacted by this unprofitable segment of its business In addition, BKM has collect...

2024 Investment Strategy: Evaluating My Portfolio and Setting New Goals

Image
It has been some time since I last wrote here. As some of you may know from following me on other platforms like  X  and Seeking Alpha , I have been writing and sharing my views elsewhere. You can find links to my work on those sites in this LINK here. Now, I wanted to provide an update on my 2023 portfolio performance and outline my strategy for 2024. To begin, my portfolio from 2023 did not change since my Restart article in Mar 2023, as I am still around 40% below my initial investment. I have not done exact calculations since my holdings are fully consolidated on Interactive Brokers, except for some Singapore stocks in my CDP account. Regardless, these returns are not satisfactory and very disappointing. Given that reality, it is clear that my previous outlook for 2023 did not come to fruition. Therefore, shaping my approach for 2024 is of utmost importance. I have reviewed my portfolio multiple times, reexamining what I am looking to achieve. After thorough consideratio...

Reflecting on My Investment in Digital Turbine (APPS): Assessing the Future Potential Despite Past Challenges

Image
Originally intended as a paid article, circumstances led me to publish it for free on my blog instead. As a result, I kindly request your support by sharing this article and clicking on the Google Ad on the side. Your gesture would be greatly appreciated! Why I Remain Invested  I was asked to share my thoughts on Digital Turbine (APPS) in light of ongoing discussions on X . As a long-term shareholder who has closely followed the company, I feel compelled to explain my rationale for persisting as an investor despite challenges.  I initially purchased APPS shares around $30, witnessing the stock rise above $90 before helplessly watching it plummet to just $5 over three years. While I sold a small portion in the $8-10 range, the bulk of my position remains deeply unrealized. It once comprised a sizable allocation that has now dwindled considerably due to further declines rather than averaging down. Chart of Digital Turbine over last 5 Years. From SeekingAlpha Thus, given the neg...

Cordlife Group's Prospects Hindered by Industry Headwinds

Image
I was going through some old documents and found my receipt showing that I had previously paid Corvyiva's services. As a new dad, Corvyiva provided an alternative form of insurance for my loved ones. Cost was not the primary concern, but when competition exists price war inevitably follow. Fundamentally, I chose Corvyiva at that time due to their offering the same service at a lower price point. It is worth noting that there is also a publicly traded company that provided similar services in the commercial storage of umbilical cord blood stem cells. Cordlife Group Ltd (CGL) lists on the SGX. I recall placing the company on my watch list when I began blogging in 2015, though I ultimately did not invest.  Cordlife Logo As the company's share price has noted better periods in the past, I was fortunate in my decision. From Google Finance Moving forward, it may be interesting to analyze CGL current business model to determine whether re-adding the firm to my portfolio watchlist is m...